DOI:http://doi.org/10.65613/742801
Dilmurod Nasimov1, Bekzot Janzakov1, Nurali Arabov2, Lutfullo Ibragimov2*, Farhod Safarov3, Shakhriyor Kholbayev4, Habibullo Hasanov1., Bobomurod. Rabiyev
1“Silk Road” International University of Tourism and Cultural Heritage, Samarkand, Uzbekistan
2Samarkand State University named after Sharof Rashidov, Samarkand, Uzbekistan
3Samarkand Institute of Economics and Service, Samarkand, Uzbekistan
4Academy of Public Policy and Administration under the President of the Republic of Uzbekistan, Tashkent, Uzbekistan
5. Andijan State University, 129 University Str., Andijan Region, Uzbekistan.
Corresponding author: Ibragimov Lutfullo (e-mail: ibragimovlutfullo@gmail.com).
ABSTRACT Although the relationship between price stability and labor market indicators in Uzbekistan is important for macroeconomic policy, the Phillips curve relationship may not be stable in transition economies. This study aimed to assess the relationship between inflation and labor market outcomes in Uzbekistan for the period 1992–2024 using indicators of Unemployment and Employment. The data were obtained from the World Bank and the International Labour Organization. In the empirical design, static relationships were first estimated using OLS (Newey–West), then Johansen cointegration and VECM were used for the Unemployment–Inflation pair, and ARDL-ECM and Bounds test suitable for mixed integration conditions were used for the Employment–Inflation pair. The OLS results showed that Inflation was negatively related to Unemployment and positively related to Employment. The VECM results indicate a long-run relationship in the Unemployment–Inflation system, while the error-correction term in the ΔUnemployment equation shows that unemployment adjusts toward equilibrium at about 14.8% per year. In the short term, Granger-type causality runs from ΔInflation to ΔUnemployment. The ARDL results show short-term lagged effects of Inflation on Employment, but the Bounds test does not confirm the long-run (level) relationship. Overall, the results indicate that the inflation-labor market relationship in Uzbekistan differs across indicators; it is important to support the labor market through economic growth and investment channels while maintaining price stability from a policy perspective.
Keywords: Employment, Inflation, Labor Market, Phillips Curve, Unemployment.
- INTRODUCTION
Balancing price stability with labour-market performance remains a central challenge for macroeconomic policy. The classic Phillips-curve idea links inflation to labour-market slack, but the strength and stability of this relationship depend on institutions, expectations, and the structure of the economy [1], [2], [3], [4]. In many settings—especially outside advanced economies—structural change and policy regime shifts can blur simple inflation–unemployment correlations, making it important to test whether the relationship is still informative for policy.
This question is particularly relevant for Uzbekistan, a post-Soviet transition economy that experienced pronounced macroeconomic volatility in the early years of independence and gradual stabilization thereafter. In such contexts, labour-market adjustment may not be fully captured by the unemployment rate alone; employment-based indicators can provide complementary information about cyclical conditions and real-side responses. In this study, labour-market performance is therefore measured using two distinct outcomes—the unemployment rate and the employment-to-population ratio (15+)—to assess whether inflation is associated with labour-market conditions differently depending on the indicator used.
Existing regional research documents inflation dynamics in the Caucasus and Central Asia and, more broadly, in post-Soviet economies, emphasizing the role of openness, exchange-rate pass-through, and changing policy regimes [5], [6], [7]. However, Uzbekistan-focused empirical evidence remains limited in that labour-market outcomes are usually treated narrowly or indirectly, rather than being analysed jointly through unemployment and employment over a long post-independence period. As a result, it remains unclear whether inflation in Uzbekistan is linked to labour-market conditions primarily through unemployment, through employment, or through feedback mechanisms between these variables.
To address this gap, the paper examines annual data for Uzbekistan over 1992–2024, measuring inflation by the GDP deflator (annual %) and labour-market outcomes by the unemployment rate and the employment-to-population ratio (15+), based on internationally comparable series from the World Bank and the International Labour Organization (ILO). The empirical strategy combines regression analysis with HAC-robust inference and a dynamic time-series analysis/Granger framework to assess both contemporaneous relationships and lead–lag interactions among inflation, unemployment, and employment.
- LITERATURE REVIEW
The relationship between inflation and labor market conditions remains one of the most debated empirical regularities in macroeconomics. The traditional Phillips curve posits a short-run trade-off between inflation and labor market slack, originally documented as a negative association between wage growth and unemployment [4] and later generalized to price inflation [8]. While the long-run stability of that trade-off was challenged by the natural-rate hypothesis and expectation-augmented frameworks [1], [3], modern research continues to revisit the extent to which inflation responds to labor market tightness—especially across different institutional settings and after large macroeconomic shocks.
- MICRO-FOUNDED PHILLIPS CURVES AND THE ROLE OF UNEMPLOYMENT
An influential strand of NKPC models explicitly integrates unemployment into the theoretical structure. By incorporating search frictions and unemployment into a New Keynesian setting, these models provide a coherent rationale for why inflation may co-move with labor market conditions while still being consistent with optimizing behavior and nominal rigidities. Blanchard & Galí, for example, show how unemployment can enter the supply-side block of a sticky-price model, clarifying the theoretical channels through which labor market slack can translate into inflation dynamics [10].
- WHY THE PHILLIPS CURVE LOOKED “FLATTER” AND HARDER TO PIN DOWN
A recurring empirical finding—especially in advanced economies—is that inflation became harder to forecast and less tightly linked to standard slack measures during parts of the Great Moderation and the post-2008 period. Stock and Watson document that the inflation process is well captured by models with time-varying volatility and persistent components, making simple Phillips-curve forecasting relationships less reliable [11]. This broader instability motivates later work arguing that the “missing disinflation” and the muted inflation response to labor market conditions can partly reflect expectation formation and information frictions rather than a complete breakdown of the underlying mechanism.
Expectations, in particular, are central. If inflation expectations are better anchored, inflation can respond less to domestic slack even if real activity remains cyclical. Evidence for sticky or imperfect information is strong in survey and macro data, and a simple implication is that inflation dynamics may depend on how quickly expectations adjust to shocks. Coibion and Gorodnichenko provide widely cited evidence consistent with information rigidity in expectations formation, which has direct implications for empirical Phillips-curve specifications that rely on measured expectations [12].
At the same time, recent research demonstrates that a Phillips-curve relationship can still be detected—sometimes more clearly in cross-sectional or regional data than in aggregate time series. Hazell et al. use U.S. state-level variation to estimate the slope of the Phillips curve and provide a careful bridge from cross-sectional estimates to the time-series object of interest [2]. Their results imply that the Phillips curve need not “disappear,” but the aggregate relationship can look weak depending on aggregation and shock composition.
- POST-PANDEMIC EVIDENCE AND RENEWED INTEREST IN THE INFLATION–SLACK LINK
The inflation surge of 2021–2022 reignited interest in whether the Phillips curve had steepened, and whether slack (or its expectations) regained explanatory power [13], [14], [15]. In this context, Crump et al. reassess the unemployment–inflation trade-off through a New Keynesian lens and show that both current and expected unemployment gaps can play an important role in explaining inflation dynamics in the post-pandemic period [16]. This line of work suggests that the apparent “flatness” of the Phillips curve may be partly regime-dependent: the slope can look different when inflation expectations, supply disturbances, and monetary policy reaction functions change.
Overall, the modern literature points to a more nuanced interpretation: inflation–slack dynamics are not a single stable coefficient, but an equilibrium outcome shaped by the nature of shocks (demand vs supply), the credibility of monetary policy, and how expectations are formed and measured. This framing is particularly relevant when moving beyond advanced economies, where institutional change and measurement issues are more pronounced.
- EMERGING AND TRANSITION ECONOMIES: OPENNESS, EXPECTATIONS, AND STRUCTURAL CHANGE
For emerging markets, inflation dynamics often reflect a combination of domestic slack, exchange-rate pass-through, imported inflation, and shifts in inflation expectations. Evidence across emerging markets indicates that long-term inflation expectations and domestic policy credibility can dominate purely global explanations, even in an interconnected world. Bems et al. analyze a large emerging-market sample within a New Keynesian Phillips-curve framework and find that domestic factors—especially expectations—remain central for inflation outcomes, while external factors play a secondary role [18].
This is especially pertinent for transition economies, where labor markets and price-setting can evolve rapidly due to reforms, sectoral reallocation, and changes in informality and participation. In such settings, the unemployment rate may not fully summarize labor market slack if job search intensity, labor force participation, or informal employment adjust strongly over the cycle. As a result, employment-based indicators (e.g., employment-to-population ratios or employment rates) can provide additional information about labor market tightness—particularly when measured unemployment is affected by institutional definitions, reporting, or participation movements.
- IMPLICATIONS FOR THIS STUDY AND THE UZBEKISTAN CASE
Uzbekistan offers a useful post-Soviet setting to study the inflation–labour market nexus because inflation has been shaped by structural reforms, a still-evolving policy framework, and strong open-economy channels such as exchange-rate pass-through—features that can weaken or distort a “textbook” Phillips-curve pattern [19]. Evidence for the Caucasus and Central Asia shows that external factors explain a sizable part of inflation movements, yet domestic demand conditions and expectations remain important, and the policy environment matters for how shocks propagate [5]. Importantly, region-focused Phillips-curve work that includes Uzbekistan documents a hybrid structure (inertia plus forward-looking components) and highlights the relevance of openness and pass-through for inflation dynamics [7]. Post-Soviet evidence from Russia also indicates that the Phillips-curve relationship can be time-varying, strengthening the case for methods that allow for changing dynamics rather than relying on one stable reduced-form coefficient [6], [20].
However, much of the available regional literature remains inflation-centred: it typically focuses on inflation determinants or inflation–slack links while giving less attention to how unemployment and employment jointly interact with inflation, especially in a long post-independence sample. Based on the reviewed literature, this article introduces several specific innovations. First, it assesses the dynamics of the Phillips curve for Uzbekistan based on data from 1992–2024, and analyzes the labor market situation not only through the Unemployment indicator, but also through the Employment indicator. Second, an econometrically appropriate approach is chosen: for the Unemployment–Inflation pair, Johansen cointegration and VECM are used, considering both long-run equilibrium and short-run adjustment; for the Employment–Inflation pair, ARDL-ECM (bounds testing) is used, suitable for the “mixed integration” case. Third, the direction issue is assessed using Granger-type predictability tests within the appropriate specifications, clearly distinguishing between short-run dynamics and long-run relationships. As a result, the study clarifies in which cases the inflation–labor market relationship in Uzbekistan manifests itself as a short-run effect, and in which cases it manifests itself as a stable long-run relationship.
- MATERIALS AND METHODS
- DATA AND VARIABLES
This study relies on annual macroeconomic data for Uzbekistan spanning the period 1992 to 2024. The selected time frame reflects both the early years of economic transition and the subsequent stages of macroeconomic stabilization and gradual reform. Using a long time horizon is particularly important in the Uzbek context, where market indicators and price dynamics have evolved unevenly and have been shaped by several major labor structural and institutional shifts.
All data were obtained from international statistical sources that ensure methodological consistency over time. Specifically, labor market indicators were taken from the International Labour Organization, while macroeconomic variables were sourced from the World Bank’s World Development Indicators database. These sources are widely used in empirical macroeconomic research and are considered reliable for cross-time analysis.
The empirical analysis considers two alternative dependent variables in order to capture different dimensions of labor market performance. The first dependent variable is unemployment, defined as the total unemployment rate expressed as a percentage of the labor force. The second is employment, measured by the employment-to-population ratio for individuals aged 15 and above. Estimating separate models for unemployment and employment allows the
analysis to examine whether inflationary dynamics affect labor market outcomes asymmetrically.
The main explanatory variable of interest is inflation, measured using the GDP deflator (annual percentage change). This indicator reflects overall price movements in the economy and is therefore more suitable for macro-level analysis than consumer price indices, which focus primarily on household consumption. Inflation is expected to influence labor market outcomes through both cost-side and demand-side channels.
In addition to inflation, several control variables are included to account for broader economic conditions. GDP per person employed (measured in constant 2021 PPP USD) is used as a proxy for labor productivity. GDP growth (annual %) captures cyclical economic expansion and contraction. Gross capital formation, expressed as a percentage of GDP, reflects investment activity and capital accumulation. Finally, population growth (annual %) is included to control for demographic pressures affecting labor supply (Table I).
TABLE I
Description of variables and data sources
| Variables | Name | Symbol | Unit of Measure | Source |
| The dependent variable | Unemployment, total (% of total labor force) | Unemployment | Percent (%) | International Labour Organization |
| Employment to population ratio, 15+, total (%) | Employment | Percent (%) | International Labour Organization | |
| The independent variables | Inflation, GDP deflator (annual %) | Inflation | Percent (%) | World Bank |
| Control variables | GDP per person employed | GDPperEmpl | Constant 2021 PPP USD | World Bank |
| GDP growth (annual %) | GDPgrowth | Percent (%) | World Bank | |
| Gross capital formation | Capital | Percent of GDP (%) | World Bank | |
| Population growth (annual %) | PopulGrowth | Percent (%) | World Bank |
To provide an initial overview of the data, Table II presents summary statistics for all variables used in the empirical analysis, including the number of observations, mean values, standard deviations and minimum and maximum values.
TABLE II
Descriptive statistics of variables (1992–2024)
| Variables | Obs | Mean | Std. Dev. | Min | Max |
| Unemployment | 33 | 6.853 | 2.883 | 2.9 | 13.3 |
| Employment | 33 | 54.951 | 1.571 | 52.579 | 59.332 |
| Inflation | 33 | 127.183 | 297.908 | 8.93 | 1238.595 |
| GDPperEmpl | 33 | 15334.24 | 6229.578 | 8755.44 | 28469.46 |
| GDPgrowth | 33 | 4.702 | 4.296 | -11.2 | 9.473 |
| Capital | 33 | 27.479 | 6.972 | 14.65 | 43.93 |
| PopulGrowth | 33 | 1.669 | 0.327 | 1.216 | 2.46 |
The descriptive results reveal substantial variability across variables. Inflation shows particularly high dispersion, reflecting the pronounced price instability observed during the early transition years. In contrast, employment levels display relatively smoother dynamics over time, while unemployment exhibits clear medium-term fluctuations.
Fig. 1 complements the statistical summary by illustrating the joint evolution of inflation and unemployment rates over the sample period.
- Inflation and unemployment trends in Uzbekistan (1992–2024).
The figure highlights a sharp surge in inflation during the first half of the 1990s. This episode is closely associated with the broader economic disruption following the dissolution of the Soviet Union and Uzbekistan’s transition to an independent monetary system. In 1994, Uzbekistan introduced its national currency, the Uzbekistani som (UZS), monetary framework [21]. The transition was accompanied by price liberalization, fiscal imbalances, and limited monetary control, which together contributed to an episode of extremely high inflation.
Such inflationary spikes were not only in Uzbekistan but have been documented across many post-Soviet economies during the early transition period [20], [22], [23]. As monetary policy institutions strengthened and macroeconomic management improved, inflation gradually declined and stabilized from the late 1990s onward.
Unemployment dynamics during this period followed a different trajectory. While inflation peaked sharply, unemployment increased more gradually as enterprises adjusted to market mechanisms, restructured production, and reduced labor demand. Over time, the stabilization of prices coincided with a more stable labor market, although unemployment remained sensitive to economic growth and investment conditions.
Taken together, the descriptive statistics and visual evidence suggest that inflationary shocks and labor market outcomes in Uzbekistan are closely linked, particularly during periods of macroeconomic adjustment. These preliminary observations provide the basis for the econometric analysis employed in the subsequent methodology section. These stylized facts motivate the use of both static and dynamic econometric techniques to formally examine the inflation–labor market nexus in the Uzbek context.
- METHODOLOGY
This study adopts a multi-step econometric framework to examine the relevance of the Phillips curve relationship in contemporary Uzbekistan, with particular attention to both employment and unemployment dynamics in the presence of inflationary pressures. Given the structural transformations of the Uzbek economy since the early 1990s, including monetary reforms, institutional restructuring, and labor market adjustments, a combination of static and dynamic methods is employed to capture both contemporaneous and temporal interactions among variables.
As a starting point, two baseline OLS regression models are estimated to evaluate the contemporaneous relationship between inflation and labor market indicators. In the first specification, unemployment is treated as the dependent variable, while in the second specification, employment is used as an alternative dependent variable. This dual modeling strategy allows the analysis to capture potential asymmetries between labor market slack and labor absorption.
The baseline models are specified as follows:
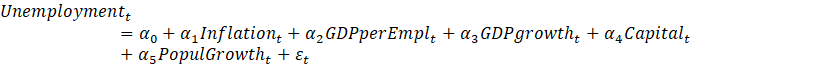
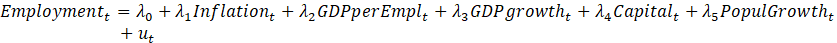
Where: intercept terms;
slope coefficients capturing the marginal effects of explanatory variables;
stochastic error terms reflecting unobserved shocks and omitted factors.
- DYNAMIC TIME-SERIES ANALYSIS AND GRANGER CAUSALITY
To examine whether the Phillips curve relationship in Uzbekistan reflects merely a contemporaneous association or a genuine dynamic interaction, the static regressions are complemented by a dynamic time-series framework and Granger-type causality analysis. This approach allows the study to move beyond short-run correlations and to explicitly test whether inflation helps predict labor-market dynamics, and vice versa, over time.
Since the choice of the dynamic specification depends on stationary and cointegration properties, the stochastic properties of all core variables are examined using the Augmented Dickey–Fuller (ADF) unit root test. The results, summarized in Table III (ADF unit root tests), indicate mixed orders of integration. Unemployment and inflation are non-stationary in levels but become stationary after first differencing, implying that both series are integrated of order one, I(1). In contrast, the employment rate is stationary in levels and therefore classified as I(0).
TABLE III
Stationarity Properties of the Variables (ADF Test Results)
| Variable | Level | First difference | Order | ||
| Z(t) | p-value | Z(t) | p-value | ||
| Unemployment | –1.338 | 0.612 | –3.550 | 0.007 | I(1) |
| Inflation | –2.369 | 0.151 | –5.040 | 0.000 | I(1) |
| Employment | –3.070 | 0.029 | – | – | I(0) |
- UNEMPLOYMENT–INFLATION: COINTEGRATION AND VECM
Since the Unemployment and Inflation series are I(1) according to the ADF test results, it was necessary to determine whether there is a long-run equilibrium relationship between these two indicators. For this purpose, the Johansen cointegration test was used (Table IV).
TABLE IV
Johansen cointegration test results (Unemployment–Inflation)
| Null Hypothesis | Trace statistic | 5% critical value |
| r = 0 | 32.1220 | 15.41 |
| r ≤ 1 | 2.4967 | 3.76 |
The results confirmed the existence of a long-run relationship between Unemployment and Inflation (Table IV). Therefore, the Vector Error Correction Model (VECM) was chosen for the Unemployment–Inflation system in the study. The VECM model allows us to estimate, in addition to short-term changes, the speed at which the system returns to its long-term equilibrium when it deviates from it (the Error Correction Term — ECT).
Before estimating the VECM, the lag length (number of lags) was selected. The AIC, HQIC, SBIC (BIC), and FPE criteria were used for lag selection, and the optimal lag length for the Unemployment–Inflation system was determined to be p = 4 (Appendix A). This choice balances the need, on the one hand, not to overcomplicate the model, and, on the other hand, not to neglect lagged effects in economic processes.
On this basis, the VECM was written as follows to analyze the Unemployment–Inflation relationship:
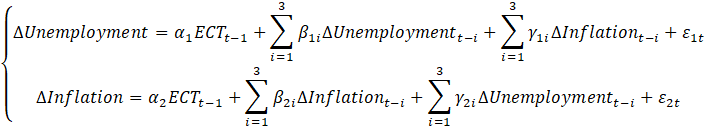
Here, is the Error Correction Term, i.e. deviation from long-run equilibrium:
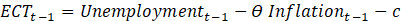
In this notation: Δ — first difference (short-run change), — represent the speed at which the system returns to equilibrium after a deviation occurs, β terms — capture the effects of the variable’s own lags, γ terms — capture the effects of the other variable’s lagged values,
— random error terms.
As a result, through the VECM approach, both the short-run and long-run aspects of the relationship between Unemployment and Inflation are assessed simultaneously, and the dynamic properties of the Phillips curve are interpreted more realistically.
- EMPLOYMENT–INFLATION: ARDL-ECM (BOUNDS TEST)
According to the ADF test results, the Employment is stationary at level I(0), while Inflation is nonstationary at level I(0) and becomes stationary after the first difference I(1) (Table III). Therefore, it may be economically problematic to evaluate the Employment–Inflation relationship as a single-order integration in the standard VAR or VECM approach. In particular, evaluating the I(0) and I(1) series in a “mixed” form in the same system increases the risk of spurious conclusions. Therefore, the ARDL-ECM approach, which is suitable for mixed integration cases, was chosen for this pair.
The main advantage of the ARDL approach is that it allows using the I(0) and I(1) series in the same model and distinguishes between short-run and long-run effects. The ARDL model lags were selected within the framework of maxlags(4) based on the information criteria (AIC and BIC). As a result, both criteria yielded the same specification: the ARDL(1,4) (p=1, q=4) model was adopted. Accordingly, the Employment–Inflation relationship was estimated using the following ARDL equation:
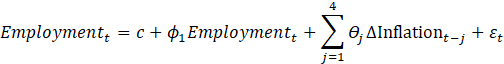
In the next step, the Bounds test proposed by [24] is used to determine whether there is a level (long-run) relationship between Employment and Inflation. If the test results indicate a long-run relationship, the ARDL results are also interpreted as an ECM (Error Correction Model). If not, then the model is mainly evaluated in the context of short-term dynamics, and the long-term interpretation is carefully limited.
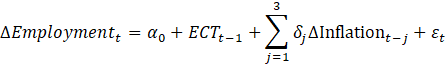
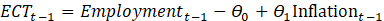
Overall, the ARDL framework is suitable for the Employment–Inflation relationship under mixed orders of integration because it allows separate estimation of short-run dynamics and testing of a possible long-run level relationship through the Bounds procedure.
- RESULTS
- OLS REGRESSION RESULTS
Before presenting the baseline OLS results, the presence of serial correlation was assessed using the Durbin–Watson statistic. The obtained values of 1.07 for the unemployment equation and 1.11 for the employment equation indicate potential positive autocorrelation in the regression residuals. In such circumstances, conventional OLS standard errors are known to be biased and may lead to misleading statistical inference [25], [26].
To address this issue, the models were estimated using Newey–West autocorrelation consistent (HAC) standard errors. This approach ensures valid statistical inference in the presence of autocorrelation and heteroskedasticity without altering the estimated coefficients themselves [27]. Given the relatively small sample size and the macroeconomic nature of the data, the Newey–West correction represents a more appropriate and conservative alternative to conventional OLS estimation.
Table V reports the OLS regression results with Newey–West standard errors for both unemployment and employment equations.
TABLE V
OLS regression results (Newey–West standard errors)
| Variables | Unemployment | Employment |
| Inflation | -0.008*** (-3.61) | 0.003*** (3.18) |
| GDPperEmpl | 0.0001 (-0.84) | -0.0002*** (-6.95) |
| GDPgrowth | -0.449*** (-4.05) | 0.113** (2.53) |
| Capital | -0.306*** (-4.69) | 0.100*** (4.02) |
| PopulGrowth | -0.686 (-0.40) | 1.264 (1.63) |
| Constant | 20.487*** (7.59) | 52.923*** (48.17) |
| F-test | 8.913 | 41.360 |
| Number of obs | 33 | 33 |
| R-squared | 0.7611 | 0.8764 |
In the unemployment equation, inflation enters with a negative and statistically significant coefficient (β = −0.008, t = −3.61), suggesting that higher inflation is associated with lower unemployment. This result is consistent with the short-run Phillips curve hypothesis and indicates the presence of a trade-off between price stability and labor market slack in Uzbekistan during the sample period.
Economic growth also contributes significantly to unemployment reduction. The coefficient on GDP growth is negative and significant (β = −0.449, t = −4.05), while gross capital formation exhibits a similarly negative and highly significant effect (β = −0.306, t = −4.69), highlighting the importance of investment-driven job creation. By contrast, GDP per person employed and population growth do not display statistically significant effects, suggesting that productivity gains and demographic changes alone are insufficient to explain short-run unemployment dynamics.
The employment equation yields results that reinforce these findings. Inflation is positively and significantly associated with employment (β = 0.003, t = 3.18), further supporting the relevance of Phillips-type dynamics. GDP growth and capital formation both exert positive and statistically significant effects on employment, whereas GDP per person employed shows a negative and significant coefficient (β = −0.0002, t = −6.95), possibly reflecting labor-saving technological improvements or efficiency-driven adjustments in the labor market. Since this indicator is measured in constant 2021 PPP USD, the interpretation is given in practical units: a $1,000 increase is associated with a decrease of about 0.2 percentage points in the employment-to-population ratio. This suggests that, in the short run, productivity gains in Uzbekistan may reflect labor-saving technologies, capital deepening, and efficiency improvements, which can temporarily reduce employment growth.
Overall model performance is satisfactory, with R-squared values of 0.761 for the unemployment equation and 0.876 for the employment equation. Additional diagnostic checks—including normality of residuals, heteroskedasticity, and multicollinearity—confirm the robustness of the estimates and are reported in Appendices B–D.
- RESULTS OF DYNAMIC TIME-SERIES ANALYSIS AND GRANGER CAUSALITY TESTS
- UNEMPLOYMENT–INFLATION: VECM RESULTS AND SHORT-RUN GRANGER CAUSALITY
Since the ADF (Table III) and Johansen results (Table IV) show that there is long-run cointegration between the Unemployment and Inflation series, this pair was estimated using the VECM (trend: constant; lag length: p = 4; rank = 1; N = 29). The VECM results show both long-run correlation (the cointegrating equation) and short-run dynamics (error-correction terms and lags).
TABLE VI
VECM long-run (cointegrating) equation
| Cointegrating vector (β) | Coefficient | Std. Err. | z | p-value |
| Unemployment | 1.000 | – | – | – |
| Inflation | -0.113 | 0.020 | -5.57 | 0.000 |
| Constant | -3.894 | – | – | – |
Note: Normalization: Unemployment = 1; Trend: constant; p = 4; Sample: 1996–2024; N = 29.
The β estimates in Table VI imply that in the long run, inflation changes are stably associated with unemployment. Due to normalization, the relationship can be conveniently interpreted as follows:
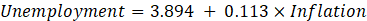
In the long run, the result was that, on average, if inflation increases by 1 percent, the unemployment rate increases by 0.113 percent (all other factors held constant). However, in the real economy, this relationship can manifest itself not only in the long run but also in the short run through various lags. Therefore, after confirming cointegration, the model was estimated as a VECM. In the VECM, the ECT shows how quickly the system returns to equilibrium when it deviates from it, and the remaining lag coefficients show short-run changes. Table VII summarizes these results.
TABLE VII
VECM error-correction and key short-run dynamics
| Variables | Lag | ΔUnemployment | ΔInflation |
| ECT | L1 | -0.148*** (-3.33) | 3.453*** (2.96) |
| ΔUnemployment | L1 | 0.209 (1.43) | 5.597 (1.45) |
| L2 | 0.011 (0.09) | -1.059 (-0.31) | |
| L3 | 0.031 (0.24) | -3.116 (-0.92) | |
| ΔInflation | L1 | 0.002 (0.83) | 0.182*** (3.33) |
| L2 | -0.0005 (-0.61) | -0.036* (-1.72) | |
| L3 | -0.003*** (-3.88) | 0.034* (1.88) | |
| Constant | -0.291*** (-2.75) | -0.012 (-0.001) | |
| Chi-square (χ²) | 88.432 | 534.501 | |
| Prob > χ² | 0.000 | 0.000 | |
| R-squared | 0.808 | 0.962 | |
| RMSE | 0.478 | 12.583 | |
| Number of obs | 29 | 29 |
Note: *** p<0.01, ** p<0.05, * p<0.1.
The ECT coefficient in the ΔUnemployment equation is −0.148 (p<0.01) and statistically significant. This means that when the system deviates from the long-run equilibrium, unemployment adjusts toward equilibrium at a rate of about 14.8% per year. The ECT coefficient in the ΔInflation equation is 3.453 (p<0.01) and is also significant. Thus, inflation is also sensitive to long-run deviations and actively “reacts” during the adjustment process back to equilibrium. In the short run, the own lags of ΔUnemployment (L1–L3) are not significant, but some lags of ΔInflation are important: ΔInflation (L3) affects changes in unemployment by −0.003 (p<0.01), while in the inflation equation, ΔInflation coefficient (L1) is 0.182 (p<0.01), indicating the presence of short-run “inertia”.
TABLE VIII
VECM-based short-run Granger causality (Wald tests)
| Causal direction | χ² statistic | p-value | Conclusion |
| ΔInflation → ΔUnemployment | 19.08 | 0.000 | Causality exists |
| ΔUnemployment → ΔInflation | 2.24 | 0.524 | No causality |
The Wald test results in Table VIII indicate a short-run Granger causality direction within the VECM: the direction ΔInflation → ΔUnemployment is significant (p<0.01), but the reverse direction (ΔUnemployment → ΔInflation) does not reveal short-run causality (p>0.05). Thus, short-run changes in inflation are more useful for predicting unemployment dynamics, but short-run changes in unemployment do not explain inflation.
- EMPLOYMENT–INFLATION: ARDL–ECM (BOUNDS TEST) RESULTS
According to the results of the Employment–Inflation relationship estimation, the specification chosen based on the information criteria was ARDL(1,4)-ECM. The results in Table IX show that, in the short run, inflation changes have lagged effects on employment changes: ΔInflation (L1) is positive and statistically significant (p<0.05), and ΔInflation (L3) is also positive and highly significant (p<0.01). This indicates that changes in inflation do not affect employment immediately, but after a certain time (through lags). Although the ADJ part (Employment L1) is negative, it is not statistically significant, i.e., the “adjustment” mechanism is not strongly confirmed in this model.
TABLE IX
ARDL(1,4)-ECM short-run results for the Employment–Inflation relationship
| Component | Variables | Lag | Employment |
| ADJ | Employment | L1 | -0.098 (-1.23) |
| Long-run | Inflation | L1 | 0.140 (1.13) |
| Short-run | ΔInflation | L0 | 0.008 (1.11) |
| ΔInflation | L1 | 0.005** (2.48) | |
| ΔInflation | L2 | -0.0003 (-0.56) | |
| ΔInflation | L3 | 0.002*** (3.99) | |
| Constant | 5.000 (1.17) | ||
| Root MSE | 0.378 | ||
| Number of obs | 29 | ||
| Adj R-squared | 0.549 | ||
| R-squared | 0.646 |
Note: *** p<0.01, ** p<0.05, * p<0.1.
In the next step, the existence of a level (long-run) relationship between Employment and Inflation was tested using the Bounds test. According to Table X, the null hypothesis of no level relationship could not be rejected (F = 2.699), since the computed F-statistic lies below the lower critical bound. This suggests that a stable long-run relationship between Employment and Inflation is not statistically confirmed in the sample. Therefore, the findings for this pair are interpreted primarily in terms of short-run dynamics.
TABLE X
ARDL Bounds test results
| Statistics | 10% Critical Bounds | 5% Critical Bounds | 1% Critical Bounds | p-value | ||||
| I(0) | I(1) | I(0) | I(1) | I(0) | I(1) | I(0) | I(1) | |
| F = 2.699 | 4.220 | 5.151 | 5.347 | 6.438 | 8.154 | 9.618 | 0.260 | 0.376 |
| t = -1.234 | -2.566 | -2.939 | -2.931 | -3.328 | -3.692 | -4.133 | 0.583 | 0.676 |
Note: The critical values are obtained from Pesaran, Shin, and Smith [24].
Additional diagnostic tests were performed to verify the model’s reliability (Appendix E). Diagnostic tests of the model residuals showed that heteroskedasticity was not detected by the Breusch–Pagan/Cook–Weisberg test (p=0.451). Also, serial correlation was not observed in the Breusch–Godfrey LM test (lags=1–2) (p=0.408; p=0.681), and the residuals did not deviate significantly from normal distribution according to the Shapiro–Wilk W test (p=0.187).
- DISCUSSION
The results of this study show that the Phillips curve relationship in Uzbekistan is not a “one-line rule”: in some cases, there are signs of short-term trade-offs, while at some horizons, inflation and labor market indicators can move in the direction of simultaneous increases (supply-side shocks). This approach is consistent with the theoretical literature, which began with the classical Phillips curve and was later enriched by expectations and the idea of the “Non-Accelerating Inflation Rate of Unemployment (NAIRU)” [1], [3], [4].
- OLS (NEWEY–WEST) RESULTS: SHORT-RUN EVIDENCE OF A TRADE-OFF
The negative association between inflation and unemployment observed in the OLS estimates aligns with early Phillips curve evidence reported in both classical and New Keynesian frameworks. However, more recent studies in emerging economies highlight that this relationship tends to persist where labour markets are less flexible and where macroeconomic shocks transmit slowly through wages and employment. Empirical evidence from Indonesia and India similarly documents a statistically significant inflation–employment trade-off, particularly during periods of structural transformation and demand-driven growth [28], [29], [30]. In this respect, Uzbekistan exhibits patterns comparable to other transition economies rather than to advanced inflation-targeting regimes.
At the same time, the finding that inflation exerts a stronger and more consistent influence on employment than on unemployment is noteworthy. Previous research has increasingly argued that unemployment rates may be an incomplete measure of labour market slack in developing economies, where informal employment, labour force participation adjustments, and underemployment play a significant role [31], [32]. Studies focusing on employment-based indicators suggest that inflationary pressures often translate into higher labour absorption without immediately reducing measured unemployment [30]. The Uzbek case appears consistent with this interpretation: employment responds more directly to inflationary dynamics, while unemployment adjustments occur more gradually.
The control factors also provide an important clue: the negative effect of GDPgrowth and Capital on Unemployment, and the positive effect on Employment, is consistent with the general theoretical view that economic growth and investment support employment. In turn, the negative effect of GDPperEmpl on Employment means that in the conditions of Uzbekistan, labor productivity growth can sometimes be accompanied by a slow increase in employment (or even a contraction in the short term) due to technological innovation and structural changes – this is especially true in economies undergoing structural transformation processes [33], [34], [35].
These results are consistent with some work on Uzbekistan: for example, Mahmudov and Nabiyeva [36] emphasize that the Phillips relationship is more pronounced in the short run, and the NAIRU approach is more important in the long run.
- UNEMPLOYMENT–INFLATION DYNAMICS: VECM LONG-RUN RELATIONSHIP AND ERROR-CORRECTION ADJUSTMENT
The Johansen cointegration test indicates a long-run relationship between Unemployment and Inflation. Since the coefficient of Inflation in the cointegrating equation (β) in the VECM is negative (normalized to Unemployment=1), in the normalized form (with Unemployment = 1), the implied long-run relationship suggests a positive association between inflation and unemployment. This result may not be entirely consistent with the constant negative relationship in the classical Phillips curve, but it is consistent with the ideas expressed by Friedman [1] and Phelps [3] that simple trade-offs are not sustainable in the long run in expectations-based approaches.
In the case of Uzbekistan, such a “positive trend” (if inflation increases, unemployment also increases) is often explained by cost-push and supply-side factors: shocks such as energy and raw material costs, import prices, administrative/utility tariffs, on the one hand, put pressure on prices, and on the other hand, they can increase production costs and negatively affect employment decisions. This is also consistent with studies on Uzbekistan, which have noted that the Phillips curve relationship is not always stable in the context of a “transition economy”. For example, one study using the VAR approach found a positive relationship between inflation and unemployment in Uzbekistan [37].
The ECT results provide the most important aspect of the VECM. The ECT coefficient in the ΔUnemployment equation is −0.148 and significant, which means that when the system deviates from equilibrium, unemployment plays a “corrective” role in the adjustment process at a rate of about 14.8% per year. This indicates that labor market adjustment in Uzbekistan is not immediate, but takes some time. At the same time, the ECT in the ΔInflation equation is also significant, indicating that inflation is sensitive to equilibrium deviations (the sign depends on the ECT’s definition and normalization).
The results are also clear for the short-run mechanism: VECM-based Wald tests (Table VIII) indicate short-run Granger causality from ΔInflation to ΔUnemployment, but not the reverse. This means that in Uzbekistan’s conditions, price shocks can serve as a “leading signal” to the labor market, and enterprises may be slow to revise their employment decisions in response to the inflationary environment. The Central Bank’s analytical materials on inflation and the labor market also emphasize the Phillips curve relationship and its short-term nature [38].
- EMPLOYMENT–INFLATION: SHORT-RUN EFFECTS AND NO LONG-RUN EVIDENCE (ARDL-ECM & BOUNDS TEST)
In the Employment–Inflation pair, the ARDL(1,4)-ECM results (Tables IX–X) revealed an important difference: according to the Bounds test, the null hypothesis of no level relationship could not be rejected (F = 2.699). This means that a level (long-run) relationship between employment and inflation is not statistically confirmed in this sample. A natural explanation exists: the employment-to-population ratio is often slower-moving and multi-determined compared to unemployment (demographics, migration, the informal sector, hidden forms of unemployment); therefore, it may not align into a stable long-run line with inflation.
At the same time, Table IX shows clear short-run dynamics: ΔInflation (L1) and ΔInflation (L3) are positive and significant. This indicates that employment responds to inflation mainly through lagged short-run channels. The purpose of the ARDL and Bounds test methodology is precisely to carefully test whether a long-run relationship exists in such cases [24].
The ARDL diagnostic results (Appendix E) indicate that the model is technically satisfactory: the Breusch–Pagan/Cook–Weisberg test suggests no heteroskedasticity, the Breusch–Godfrey LM test indicates no serial correlation, and the Shapiro–Wilk W does not reject residual normality. This allows the short-run conclusions to be discussed with confidence.
- COMPARISON WITH THE LITERATURE AND IMPLICATIONS FOR UZBEKISTAN
The results combine two main ideas in the literature. First, the classical Phillips curve may show a short-run trade-off [4], and second, the “simple trade-off” may not be sustainable in the long run due to expectations and institutional factors [1], [3]. The studies that have discussed the NAIRU and Phillips relationship in Uzbekistan [36], [39] also emphasize this: a relationship may be apparent in the short run, but sustainability in the long run is more complex.
Sadykov [40] also analyzes the dynamics of inflation in Uzbekistan within the framework of the New Keynesian Phillips curve, discussing the role of expectations and “backward-looking” components in the inflation process, which also helps to explain how the Phillips relationship is formed in the country context.
In practical terms, these results indicate that inflation shocks in Uzbekistan do not pass through to the labor market at the same rate or speed. Unemployment clearly showed a long-run equilibrium return mechanism (ECT), while Employment responded more through short-run and lagged effects, and the long-run was not confirmed by the Bounds test. Therefore, it is important to avoid a simplistic trade-off interpretation of “increase employment by increasing inflation” in policy recommendations and to adopt an approach that considers price stability, production costs, and labor market adjustment together.
- LIMITATIONS AND FUTURE RESEARCH
Since this study relies on annual data, some short-term fluctuations and rapid shocks may not be fully captured in the results. Also, because the time series used is relatively limited (fewer observations), the estimates are likely to be sensitive to the number of parameters in some models. Future studies would benefit from using quarterly data and from including additional indicators that more fully reflect the labor market (e.g., labor force participation, underemployment, or informal employment proxies). In addition, robustness checks using structural breaks and alternative specifications to better assess the impact of reforms and external shocks would strengthen the results.
- CONCLUSION
This study examined the dynamic relationship between inflation and labour market outcomes in Uzbekistan over the period 1992–2024, with a particular focus on the relevance of Phillips curve dynamics in a transition economy. The research assessed the relationship between inflation and labor market indicators in Uzbekistan using different approaches and showed that the relationship is not “unilinear”. While static estimates indicate a Phillips-type relationship in the short run, dynamic results reveal that this relationship behaves differently over time.
First, the existence of a long-run relationship in the Unemployment–Inflation pair was confirmed, and the VECM results showed that when the system deviates from equilibrium, labor market indicators return to equilibrium over time. In the short run, it was observed that changes in inflation can explain unemployment dynamics as a “signal” in advance. This increases the possibility that price dynamics are delayed in the labor market in Uzbekistan.
Second, the ARDL(1,4)-ECM results in the Employment–Inflation pair showed that the impact on employment is mainly manifested through short-term lagged channels, but a stable long-run (level) relationship was not statistically confirmed in this sample. Thus, the link between employment and inflation is likely to be more of a short-term phenomenon.
In practical terms, the results suggest that rather than simply interpreting inflation as a “tool for increasing employment”, it is important to maintain price stability, reduce production costs, and support the labor market through investment and economic growth. In the future, it would be useful to further strengthen the results by using quarterly data, alternative labor-market indicators (such as participation or underemployment), and examining structural changes.
APPENDIX A
Lag Length Selection Criteria for the ΔUnemployment – ΔInflation VECM model
| Lag | Log-Likelihood | LR statistic | df | p-value | FPE | AIC | HQIC | SBIC |
| L0 | -185.369 | 1402.92 | 12.922 | 12.9515 | 13.0163 | |||
| L1 | -134.947 | 100.84 | 4 | 0.000 | 57.1807 | 9.72049 | 9.80908 | 10.0034 |
| L2 | -129.796 | 10.301 | 4 | 0.036 | 53.1084 | 9.64113 | 9.78879 | 10.1126 |
| L3 | -124.766 | 10.061 | 4 | 0.039 | 50.0859 | 9.57006 | 9.77679 | 10.2301 |
| L4 | -107.282 | 34.967* | 4 | 0.000 | 20.2211* | 8.64015* | 8.90595* | 9.48882* |
Note: * optimal lag.
APPENDIX B
Multicollinearity Diagnostics (Variance Inflation Factors)
| Variable | VIF | 1/VIF |
| PopulGrowth | 4.62 | 0.2166 |
| Inflation | 4.38 | 0.2283 |
| GDPgrowth | 4.04 | 0.2477 |
| GDPperEmpl | 3.64 | 0.2749 |
| Capital | 2.19 | 0.4568 |
| Mean VIF | 3.77 |
APPENDIX C
Residual Normality Tests (Shapiro–Wilk Statistics) for the OLS models
| Dependent variable | Obs | W | V | z | Prob > z |
| Unemployment | 33 | 0.9555 | 1.519 | 0.869 | 0.1924 |
| Employment | 33 | 0.9377 | 2.129 | 1.571 | 0.0581 |
APPENDIX D
Breusch–Pagan Test for Heteroskedasticity for the OLS models
| Dependent variable | χ²(1) | Prob > χ² |
| Unemployment | 0.03 | 0.8549 |
| Employment | 0.04 | 0.8481 |
APPENDIX E
Residual diagnostic tests for the ARDL model
| Test | Statistic | p-value |
| Breusch–Pagan/Cook–Weisberg (hettest) | χ²(1)=0.57 | 0.4507 |
| Breusch–Godfrey LM (lags=1) | χ²(1)=0.685 | 0.4080 |
| Breusch–Godfrey LM (lags=2) | χ²(2)=0.767 | 0.6814 |
| Shapiro–Wilk W test | W=0.95036 | 0.18706 |
ACKNOWLEDGMENT
The authors acknowledge the use of OpenAI’s ChatGPT (GPT-5.2) and Grammarly (Pro) in improving the clarity and grammatical quality of the manuscript. These tools were used solely for language refinement purposes. All ideas, analyses, and final interpretations remain the authors’ responsibility, and the entire manuscript was carefully reviewed and verified by the authors.
REFERENCES
[1] M. Friedman, “The role of monetary policy,” The American economic review, vol. 58, no. 1, pp. 1–17, 1968.
[2] J. Hazell, J. Herreño, E. Nakamura, and J. Steinsson, “The Slope of the Phillips Curve: Evidence from U.S. States,” The Quarterly Journal of Economics, vol. 137, no. 3, pp. 1299–1344, Jul. 2022, doi: 10.1093/qje/qjac010.
[3] E. S. Phelps, “Phillips Curves, Expectations of Inflation and Optimal Unemployment over Time,” Economica, vol. 34, no. 135, p. 254, Aug. 1967, doi: 10.2307/2552025.
[4] A. W. Phillips, “The Relation between Unemployment and the Rate of Change of Money Wage Rates in the United Kingdom, 1861-1957,” Economica, vol. 25, no. 100, p. 283, Nov. 1958, doi: 10.2307/2550759.
[5] M. Atamanchuk, A. Hajdenberg, D. Kadissi, G. Lisi, and N. Rao, “Drivers of Inflation in the Caucasus and Central Asia,” International Monetary Fund, Jan. 2025. [Online]. Available: https://EconPapers.repec.org/RePEc:imf:imfwpa:2025/003
[6] M. Sanjani, “Putting the Curve Back in Russia’s Phillips Curve: A Time Varying Approach,” IMF Country Report, vol. 17, no. 198, pp. 78–93, 2017.
[7] I. Sovbetov, “The hybrid Phillips curve and inflation in post-Soviet Central Asia and the South Caucasus,” Post-Communist Economies, vol. 37, no. 8, pp. 1149–1171, Nov. 2025, doi: 10.1080/14631377.2025.2576203.
[8] P. A. Samuelson and R. M. Solow, “Analytical aspects of anti-inflation policy,” The American economic review, vol. 50, no. 2, pp. 177–194, 1960.
[9] S. Mavroeidis, M. Plagborg-Møller, and J. H. Stock, “Empirical Evidence on Inflation Expectations in the New Keynesian Phillips Curve,” Journal of Economic Literature, vol. 52, no. 1, pp. 124–188, Mar. 2014, doi: 10.1257/jel.52.1.124.
[10] O. Blanchard and J. Galí, “Labor Markets and Monetary Policy: A New Keynesian Model with Unemployment,” American Economic Journal: Macroeconomics, vol. 2, no. 2, pp. 1–30, Apr. 2010, doi: 10.1257/mac.2.2.1.
[11] J. H. Stock and M. W. Watson, “Why Has U.S. Inflation Become Harder to Forecast?,” J of Money Credit Banking, vol. 39, no. s1, pp. 3–33, Feb. 2007, doi: 10.1111/j.1538-4616.2007.00014.x.
[12] O. Coibion and Y. Gorodnichenko, “Information Rigidity and the Expectations Formation Process: A Simple Framework and New Facts,” American Economic Review, vol. 105, no. 8, pp. 2644–2678, Aug. 2015, doi: 10.1257/aer.20110306.
[13] F. D’Amuri, M. De Philippis, E. Guglielminetti, and S. Lo Bello, “Slack and prices during Covid-19: Accounting for labor market participation,” Labour Economics, vol. 75, p. 102129, Apr. 2022, doi: 10.1016/j.labeco.2022.102129.
[14] M. Fukao and E. Shioji, “Is There a Trade-Off between COVID-19 Control and Economic Activity? Implications from the Phillips Curve Debate,” Asian Economic Policy Review, vol. 17, no. 1, pp. 66–85, Jan. 2022, doi: 10.1111/aepr.12361.
[15] M. Harding, J. Lindé, and M. Trabandt, “Understanding post-COVID inflation dynamics,” Journal of Monetary Economics, vol. 140, pp. S101–S118, Nov. 2023, doi: 10.1016/j.jmoneco.2023.05.012.
[16] R. K. Crump, S. Eusepi, M. Giannoni, and A. Şahin, “The unemployment–inflation trade-off revisited: The Phillips curve in COVID times,” Journal of Monetary Economics, vol. 145, p. 103580, Jul. 2024, doi: 10.1016/j.jmoneco.2024.103580.
[17] G. Kamber and B. Wong, “Global factors and trend inflation,” Journal of International Economics, vol. 122, p. 103265, Jan. 2020, doi: 10.1016/j.jinteco.2019.103265.
[18] R. Bems, F. Caselli, F. Grigoli, B. Gruss, and W. Lian, “Is Inflation Domestic or Global? Evidence from Emerging Markets,” IMF Working Papers, vol. 18, no. 241, p. 1, 2018, doi: 10.5089/9781484381595.001.
[19] E. Cabezon and M. Al Rasasi, “Uzbekistan’s Transition to Inflation Targeting,” IMF Working Papers, vol. 2022, no. 229, p. 1, Nov. 2022, doi: 10.5089/9798400224584.001.
[20] N. Leheyda, “Determinants of Inflation in Ukraine: A Cointegration Approach,” in The Periphery of the Euro, 0 ed., Routledge, 2017, pp. 327–360. doi: 10.4324/9781351145886-25.
[21] Ibragimov, L., Sherxolov, O., Musayev, B., Boboyev, S., Sobirova, M., & Boratova, G. (2024). Industrial development and assessment of its impact in Samarkand region-a GIS mapping-based study. In E3S Web of Conferences (Vol. 590, p. 06002). EDP Sciences.
[22] M. Dabrowski, “Disinflation, Monetary Policy and Fiscal Constraints. Experience of the Countries in Transition,” CASE-Center for Social and Economic Research, 1999. [Online]. Available: https://EconPapers.repec.org/RePEc:sec:cnrepo:0016
[23] K. M. Kiani, “Inflation in Transition Economies: An Empirical Analysis,” Transit Stud Rev, vol. 16, no. 1, pp. 34–46, May 2009, doi: 10.1007/s11300-009-0057-2.
[24] M. H. Pesaran, Y. Shin, and R. J. Smith, “Bounds testing approaches to the analysis of level relationships,” J of Applied Econometrics, vol. 16, no. 3, pp. 289–326, May 2001, doi: 10.1002/jae.616.
[25] C. Christodoulou-Volos, “Misleading dynamics: The erosion of Durbin-Watson power through time aggregation,” 2576-8484, vol. 9, no. 9, pp. 226–244, Sep. 2025, doi: 10.55214/2576-8484.v9i9.9787.
[26] VVL, A. P., Suhail, M., Lutfullo, I., & Shodiyor, B. (2024). A Comparative Study of Three Supervised Algorithms for Mixed Crop Classification. In E3S Web of Conferences (Vol. 590, p. 01004). EDP Sciences.
[27] U. K. Müller, “HAC Corrections for Strongly Autocorrelated Time Series,” Journal of Business & Economic Statistics, vol. 32, no. 3, pp. 311–322, Jul. 2014, doi: 10.1080/07350015.2014.931238.
[28] N. Aqilah, G. B. N. Simanjuntak, S. Ardhana, N. K. P. Sandy, A. Sifadilla, and A. S. Nuraya, “Analysis of the Relationship Between Inflation and Unemployment in Indonesia through the Modern Phillips Curve Approach,” FJAS, vol. 4, no. 6, pp. 1595–1606, Jun. 2025, doi: 10.55927/fjas.v4i6.169.
[29] R. H. Dholakia, “Does Inflation-Unemployment Trade-Off Exist in India?,” Indian Institute of Management Ahmedabad, Research and Publication Department, Dec. 1987. [Online]. Available: https://EconPapers.repec.org/RePEc:iim:iimawp:wp00796
[30] R. E. Wimanda, P. M. Turner, and M. J. B. Hall, “The shape of the Phillips curve: the case of Indonesia,” Applied Economics, vol. 45, no. 29, pp. 4114–4121, Oct. 2013, doi: 10.1080/00036846.2012.744137.
[31] J. A. Ganie, D. Singh, Y. Kumar, C. Ananth, M. Shahparan, and R. Buribay, “Workforce Planning and Optimization with Digital Twin: Insights from Social Media Campaigns for Sustainable Development Goals,” in HR 5.0 Integration, C. Sachdeva, V. Grover, B. Balusamy, V. P. Gangwar, and P. Kumar, Eds., Emerald Publishing Limited, 2026, pp. 151–165. doi: 10.1108/978-1-83708-112-720261010.
[32] N. S. Sylla, “Measuring labour absorption problems in developing countries: Limitations of the concept of unemployment,” International Labour Review, vol. 152, no. 1, pp. 27–41, Mar. 2013, doi: 10.1111/j.1564-913X.2013.00167.x.
[33] A. Amirov, R. Nurimbetov, N. Arabov, B. Boltaev, H. Hasanov, and I. Nasimov, “Exploring the Dynamics of Human Capital and Economic Growth in Central Asian Countries: An Empirical Analysis Using Panel Data,” Global Business Review, p. 09721509251415274, Jan. 2026, doi: 10.1177/09721509251415274.
[34] F. D. Mobo, M. Shahparan, A. Gomez, and M. Bongalonta, “Supply Chain Risk Management in the Business Sector: The Modern Perspective,” in Advances in Business Strategy and Competitive Advantage, R. Perez-Uribe, D. Ocampo-Guzman, and L. J. Lozano-Correa, Eds., IGI Global, 2024, pp. 313–324. doi: 10.4018/979-8-3693-4046-2.ch014.
[35] M. Mukhammedov, B. Safarov, H. Hasanov, S. Isxakova, M. Buzrukova, and T. H. Hassan, “METHODS FOR OPTIMIZING PROPERTY RELATIONS AS A KEY ASPECT OF STIMULATING THE DEVELOPMENT OF THE TOURISM INDUSTRY,” GTG, vol. 58, no. 1, pp. 484–491, Mar. 2025, doi: 10.30892/gtg.58145-1430.
[36] N. Mahmudov and N. Nabiyeva, “Inflation and Unemployment: Evidence from Uzbekistan,” GED, vol. 1, no. 1, Feb. 2024, doi: 10.55439/GED/vol1_iss1/a884.
[37] A. Suyunov, “Inflation, Unemployment and Economic Growth Causality: Do Phillips and Okun’s laws work in Uzbekistan’s Economy?,” SSRN Journal, 2023, doi: 10.2139/ssrn.4400003.
[38] The Central Bank of the Republic of Uzbekistan, “Monetary policy guidelines for 2026 and the period of 2027-2028,” The Central Bank of the Republic of Uzbekistan, Tashkent, Monetary Policy Guidelines 31/1, 2025. [Online]. Available: https://cbu.uz/upload/medialibrary/db3/1eokm4zwymw53zbfzf4aec1wdkgj5myr/MPG-2026-Final-merged.pdf
[39] N Tojiyeva, Z., & Ibragimov, L. (2021). Labour market and employment in Uzbekistan. Geografický časopis, 73(4), 359-374. DOI: https://doi.org/10.31577/geogrcas.2021.73.4.19
[40] S. Sadykov, “Modelling Of Inflationary Processes In Uzbekistan On The Basis Of The New Keynesian Philips Curve,” Economics and Management, vol. 14, no. 2, pp. 72–99, 2018.